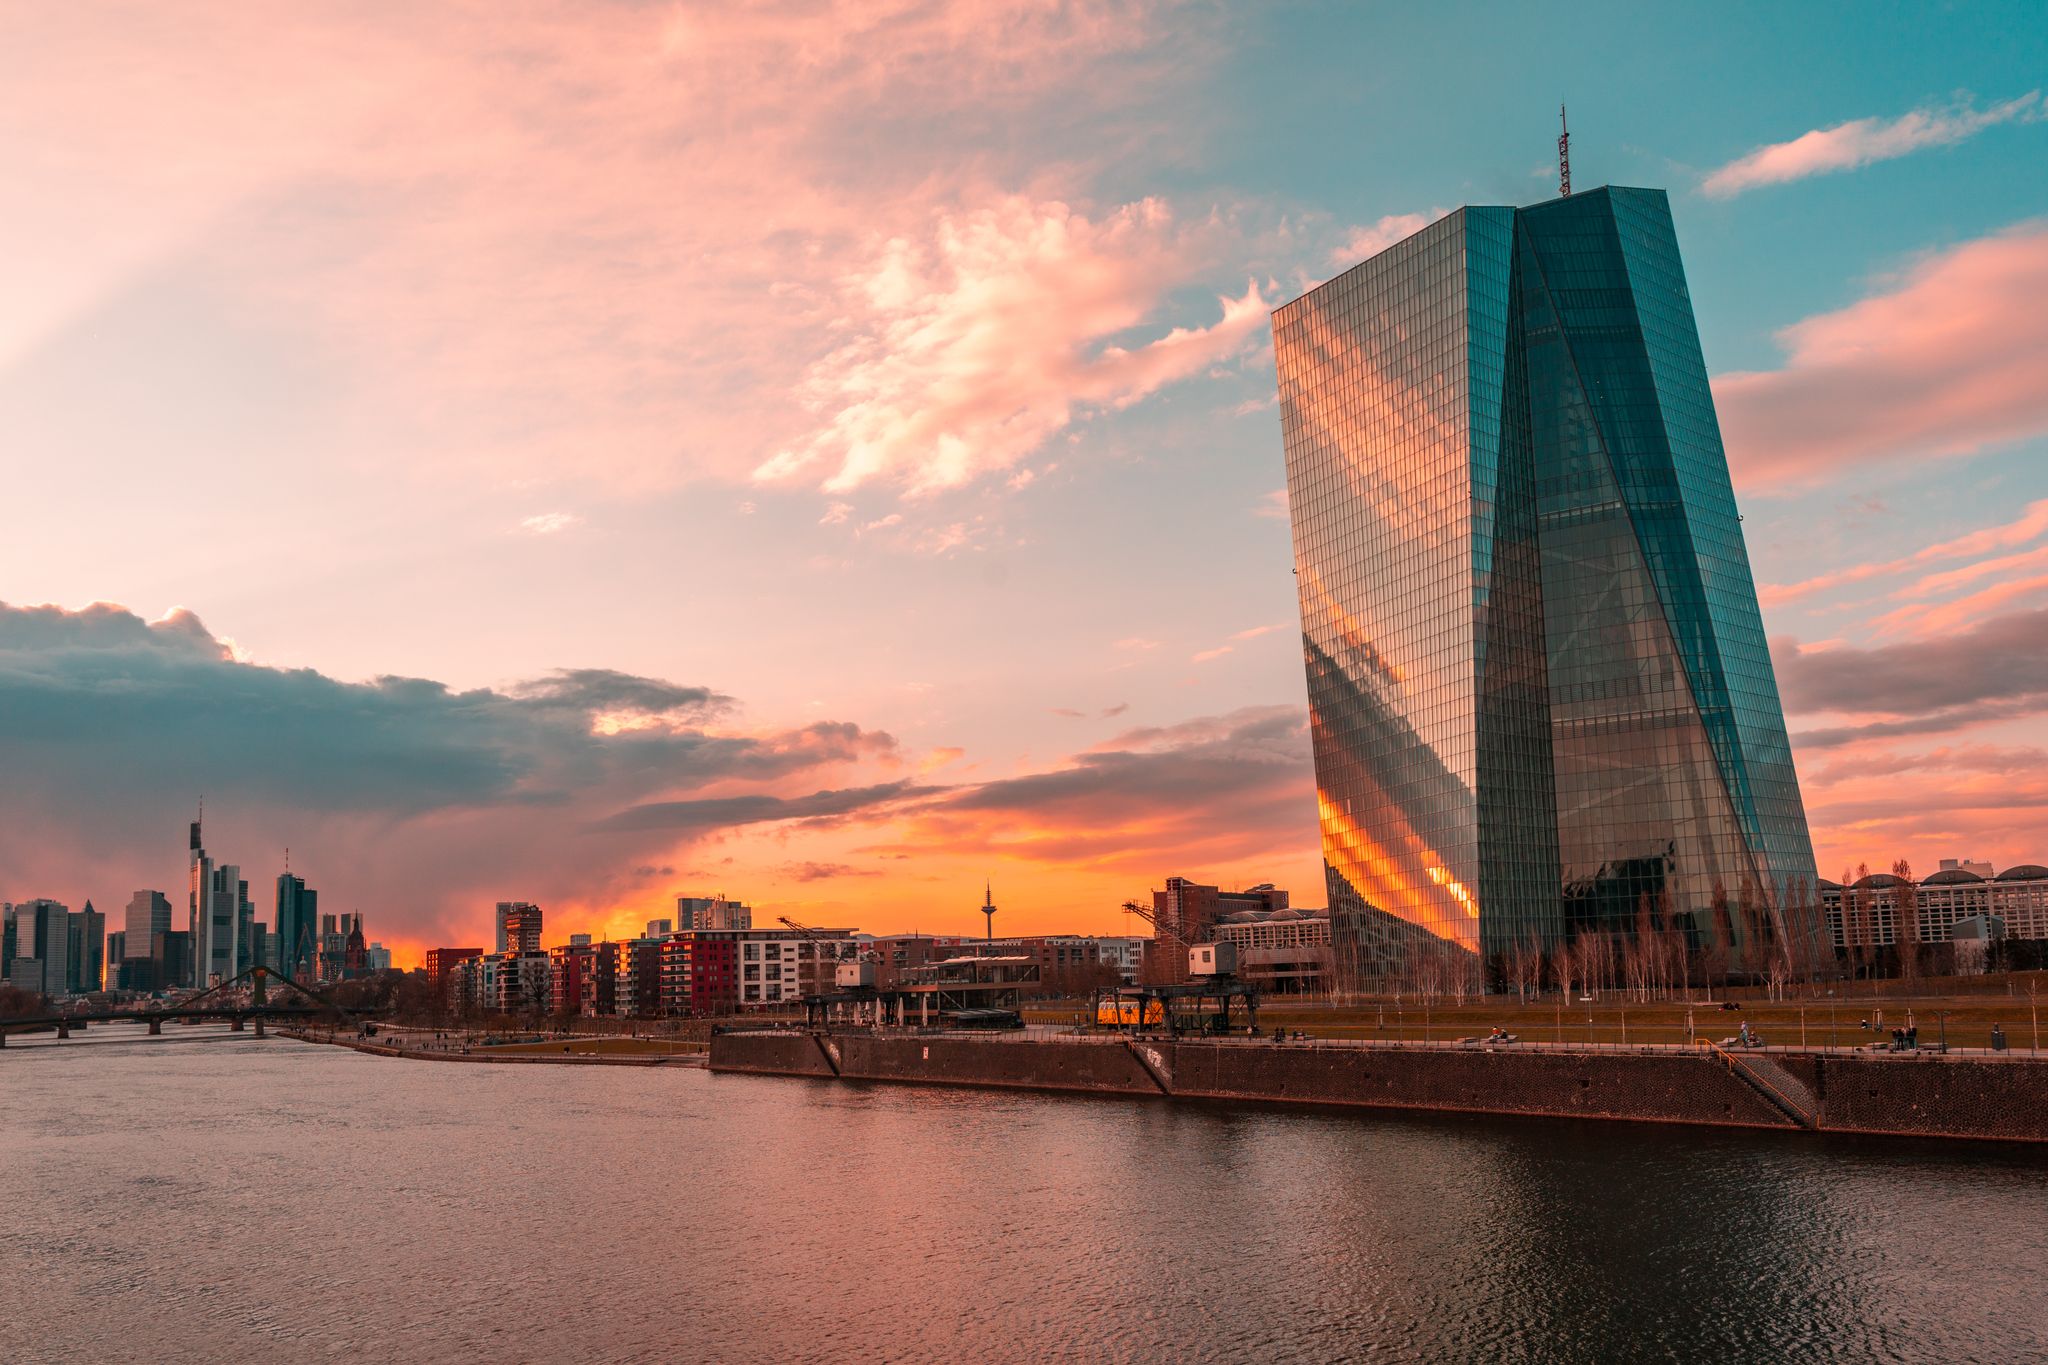
Photo by Masood Aslami on Pexels
Central Bank Digital Currencies 2026: Future of Money
Explore how Central Bank Digital Currencies (CBDCs) are reshaping global banking, cross-border payments, and consumer privacy in 2026.
Key Takeaways
- →CBDC pilots worldwide are transitioning into production-ready financial systems in 2026.
- →China's digital yuan and Bahamas' Sand Dollar lead global retail adoption.
- →The ECB is testing cross-border CBDC payments to enable near-instant settlements.
- →Sweden's e-krona pilot provides crucial real-world data on retail banking impacts.
- →Privacy remains a central concern, driving research into zero-knowledge security techniques.
Imagine paying your neighbor for a cup of coffee with a single tap, and the transaction is recorded instantly in a secure ledger that never fails. That scenario is already unfolding in several countries, thanks to Central Bank Digital Currencies (CBDCs) that are moving from theory to practice.
A global rollout in motion
By the end of 2024, the Bank for International Settlements (BIS) reported that 48 of the 68 central banks surveyed had launched at least a pilot program. In 2025, the number climbed to 61, and most of those pilots are now moving toward a production‑ready phase. China’s digital yuan, for example, has processed more than 4 billion transactions in the first year of its public release, while the Bahamas’ Sand Dollar has seen 12 % of the population adopt it for everyday purchases.
The European Central Bank (ECB) is testing a cross‑border payment system that could reduce settlement times from the current 3–5 business days to under a minute. Meanwhile, Sweden’s e‑krona pilot, launched in 2020, has already reached 20 % of the country’s population, providing a real‑world laboratory for studying the impact on retail banking.
Privacy at the heart of the debate
The promise of instant, borderless payments is tempered by growing concerns about data privacy. Unlike traditional bank accounts, a CBDC ledger can potentially record every transaction a user makes, raising fears of surveillance. The BIS notes that privacy‑preserving techniques—such as zero‑knowledge proofs and selective disclosure—are being incorporated into the design of new systems, but the regulatory framework lags behind. In the United States, the proposed “Digital Dollar” bill includes a “no‑surveillance” clause, but critics argue it falls short of protecting consumer anonymity.
How CBDCs are reshaping banking
For commercial banks, the arrival of CBDCs signals a shift in the competitive landscape. Deposit rates may compress as consumers can hold digital currency directly with the central bank, potentially eroding the traditional interest margin. Banks that adapt quickly can turn CBDCs into new revenue streams: offering digital wallet services, providing cross‑border payment solutions, and leveraging the data for personalized financial products.
Consider the story of a small vendor in Nairobi who once relied on M‑Pesa for daily sales. After the Central Bank of Kenya rolled out a pilot for a digital Kenyan shilling, the vendor now receives payments in real time, eliminating the need for intermediaries and cutting transaction costs from 2 % to less than 0.5 %. The vendor also reports faster access to working capital, as the central bank’s instant settlement system allows for immediate invoice financing.
Practical use cases
- Micropayments – A digital platform in India is experimenting with a CBDC‑based payment gateway that can process 100 k transactions per second, enabling pay‑as‑you‑play gaming and content tipping without the fees that plague card networks.
- Remittances – The Central Bank of the Dominican Republic’s pilot has reduced cross‑border remittance fees from 5 % to 0.5 %, while settlement times dropped from 3 days to a few seconds.
- Public services – Singapore’s Monetary Authority is testing a CBDC‑enabled system for distributing unemployment benefits directly to recipients’ wallets, ensuring timely and traceable disbursements.
Looking ahead
By 2026, the International Monetary Fund (IMF) predicts that CBDCs could increase global payment system efficiency by up to 25 % and reduce the cost of cross‑border transactions by an estimated 30 %. Yet the success of these digital currencies hinges on striking a balance between innovation, consumer privacy, and financial stability.
The next few years will see CBDCs transition from experimental pilots to integral components of the global financial ecosystem—challenging banks to rethink their business models, regulators to refine privacy safeguards, and consumers to embrace a new form of money that is as reliable as it is revolutionary.
Was this article helpful?
Frequently Asked Questions
Stay in the loop
New free tools and practical guides, now and then. No spam, unsubscribe anytime.
Written by
TechVeb Team
The TechVeb team writes practical guides on artificial intelligence, cloud computing, cybersecurity and programming, plus product reviews and free browser-based tools. Edited by Norina Aslam.

Continue Reading
View all →
Digital Twins in Healthcare: 2026 Virtual Patient Tech
Explore digital twins in healthcare for 2026. Discover how virtual patient models revolutionize surgical planning, drug R&D, and personalized medicine.
Best Tech Tools for Digital Nomads in 2026
Discover the best tech tools for digital nomads in 2026. Upgrade your remote work stack with top laptops, VPNs, power banks, and productivity apps.

Anthropic Watermarks Claude Text for EU AI Act Compliance
Anthropic will watermark text from Claude AI models using C2PA standards to comply with the EU AI Act's new transparency rules. Learn how it works.

AI Agents Guide: How Autonomous AI Systems Work
Learn how AI agents use planning, reasoning, and tools to execute complex tasks autonomously. Discover key use cases, architectures, and market impact.
Future of AI in 2026: Top Trends & Breakthroughs
Explore top AI trends for 2026 and beyond. From multimodal models to autonomous agents, see how AI is transforming tech and society.
Moody's Warns Banks: AI Push Creates Big Tech Dependency
Moody's warns that banks adopting artificial intelligence risk extreme vendor dependency on Big Tech cloud providers, exposing them to outages and cyber...
Comments
Loading comments…